What is the scope and industry significance of the Organizational Change Management Software Market?
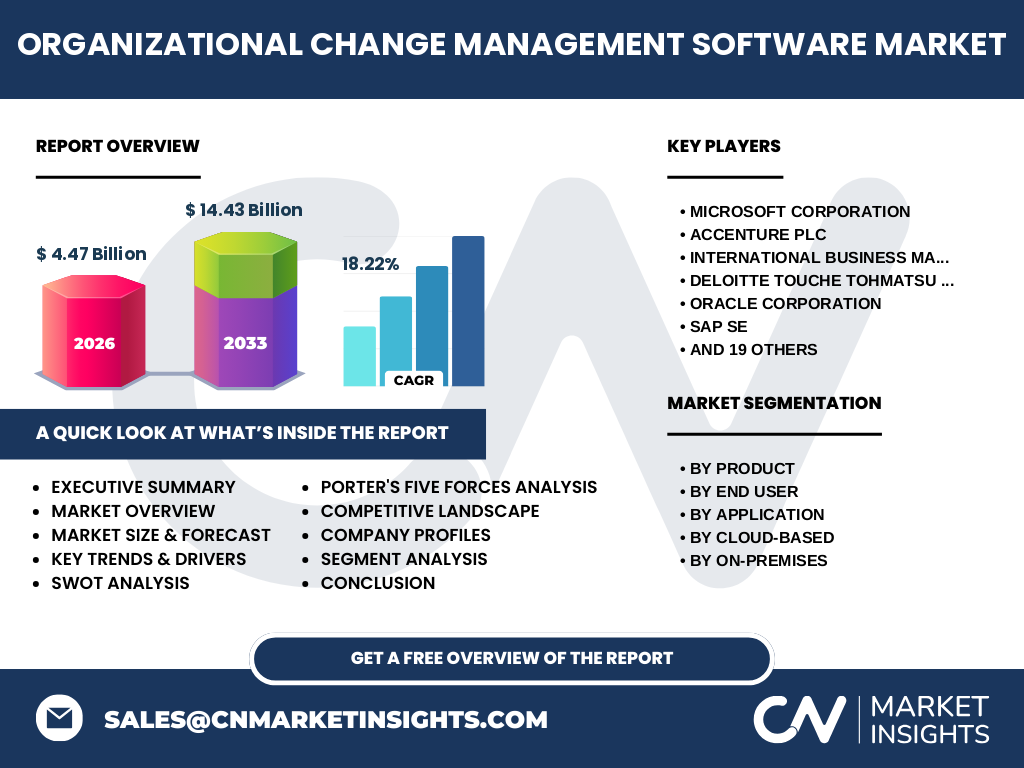
Our analysis indicates that the Organizational Change Management Software Market represents a critical digital transformation category valued at $4.47 Billion in 2026. This market provides essential tooling for enterprises navigating structural pivots, ensuring compliance with strict governance frameworks like GDPR and SOX while minimizing workforce disruption during digital migrations.
Structural Growth Drivers and Market Restraints
Based on our research, the 18.22% CAGR trajectory is heavily accelerated by hybrid workforce demands and complex enterprise cloud migrations. However, market restraints persist, notably steep implementation costs and steep learning curves associated with legacy workflow integrations across heavily regulated sectors like BFSI and healthcare.
Emerging Industry Trends and Transformation Patterns
The shift toward AI-driven sentiment analysis and automated impact forecasting defines current industry trends. Enterprises increasingly demand platforms equipped with real-time feedback loops to monitor employee adoption metrics, allowing organizations like Microsoft and ServiceNow to capture substantial market share through intelligent workflow automation.
How did the COVID-19 pandemic permanently reshape adoption dynamics?
The pandemic acted as a massive catalyst, forcing rapid remote-work transitions that exposed the fragility of manual change management processes. Our research shows that post-pandemic recovery heavily favors cloud-native solutions, driving structural demand for SaaS-based deployment models capable of supporting distributed enterprise architectures.
Competitive Benchmarking and Market Concentration
The Organizational Change Management Software Market industry trends point toward an increasingly consolidated landscape dominated by tech giants like SAP, Oracle, and Salesforce, alongside agile specialists such as Whatfix and Change Compass. These market leaders leverage extensive partner ecosystems to deliver scalable enterprise transformation frameworks.
Executive Summary of Key Analytical Findings
High-level synthesis confirms that the Organizational Change Management Software Market market size will scale dramatically from $4.47 Billion in 2026 to $14.43 Billion by 2033. Organizations failing to adopt automated change enablement tools risk critical productivity losses during enterprise resource planning (ERP) deployments.
Market Forecast Analysis from 2027 to 2033
Projected growth data demonstrates a robust expansion path, scaling the market from its 2026 baseline to $14.43 Billion by 2033 at a stellar 18.22% CAGR. This surge is fueled by continuous modernization cycles across manufacturing, retail, and government sectors requiring agile workforce alignment.
Granular Segmentation Analysis by Product, End User, and Application
Market segmentation categorizes solutions into Cloud-based (SaaS, Hybrid, Public, Private) and On-premises (Enterprise, Perpetual, One-Time, Subscription) models. End users span BFSI, IT and Telecom, Government, Healthcare, Education, Retail, Energy, Manufacturing, and Construction, addressing both Small and Medium Enterprises (SMEs) and Large Enterprises.
Regional Market Distribution and Performance Metrics
Geographic analysis highlights North America as the dominant revenue contributor, supported by early cloud adoption and high IT spending. Meanwhile, the Asia-Pacific region exhibits the fastest growth velocity, driven by rapid industrial automation and expansive digital infrastructure investments in developing economies.
In-Depth Regional Review of Regulatory and Logistical Constraints
Localized market constraints heavily influence regional software deployments. For instance, stringent data residency mandates in the European Union under GDPR favor hybrid and private cloud configurations, requiring vendors like OpenText and SAP to ensure strict compliance in their change management deployments.
Strategic Positioning of Leading Company Profiles
Industry heavyweights utilize distinct strategic positioning to capture demand. Accenture and Deloitte integrate proprietary change methodologies with enterprise platforms, while product leaders like Freshworks, ManageEngine, and Whatfix focus on frictionless user onboarding and embedded contextual guidance to maximize software utilization rates.
Porter's Five Forces Assessment of Industry Competitiveness
Porter's analysis reveals moderate-to-high competitive rivalry driven by continuous product innovation. Supplier power remains low due to abundant cloud infrastructure providers, whereas buyer power is high, compelling vendors like Oracle and Salesforce to continually enhance their user experience and analytics capabilities.
SWOT Analysis of the Change Management Software Ecosystem
Key strengths lie in deep enterprise integrations and robust analytics, while weaknesses include high deployment friction. Opportunities abound in AI-powered adoption forecasting, though threats from macroeconomic headwinds and data security vulnerabilities require continuous platform hardening across all market participants.
Value Chain Analysis from Development to End-User Delivery
The industry value chain flows from core software R&D and cloud infrastructure hosting through certified implementation partners like PwC and KPMG, ultimately delivering value to end-users via streamlined training, continuous feedback analytics, and automated adoption tracking dashboards.
Strategic Investment Insights and High-Potential Opportunity Zones
Investors should target niche SaaS innovators specializing in AI-driven employee sentiment tracking and automated compliance monitoring. High-potential opportunities exist within emerging verticals like healthcare and education, where legacy workflows demand specialized digital transformation support.
Conclusion and Strategic Takeaways for Industry Stakeholders
Reaching $14.43 Billion by 2033, the market rewards vendors that successfully combine robust compliance frameworks with intuitive user adoption tools. Stakeholders must prioritize cloud scalability and AI integration to maintain competitive differentiation in a rapidly evolving technological landscape.
Research Methodology and Baseline Triangulation Framework
Our baseline estimates are triangulated using a rigorous methodology combining trade registry data, primary stakeholder interviews with enterprise CIOs, and secondary macroeconomic indicators. This multi-tiered approach ensures high fidelity across our market sizing and growth projections.
Scope of the Report and Analytical Coverage Parameters
This research report covers global deployment models across named enterprise sectors from 2026 through 2033. Limitations include macroeconomic volatility and unforeseen regulatory shifts, which are continuously factored into our dynamic forecasting models to preserve analytical accuracy.
Recent Industry Developments, Partnerships, and Product Launches
Recent strategic moves emphasize artificial intelligence integration, with major players launching generative AI assistants designed to automate stakeholder communication plans. Strategic partnerships between consulting firms and pure-play software vendors like Whatfix and ServiceNow continue to reshape competitive boundaries.